Facebook
 X
 Pinterest
 Copy Link
What Is a 2-1 Buydown and How Can It Help Home Buyers and Sellers?
With mortgage rates playing such a big role in affordability, buyers and sellers are looking for creative ways to put a deal together without necessarily relying on a large price reduction.
One option you may hear about is a 2-1 temporary mortgage rate buydown.
A 2-1 buydown can lower a buyer’s mortgage payment during the first two years of homeownership. And in some transactions, a seller may be able to provide a credit that helps fund it.
So, how does it work—and when might it make sense?
What Is a 2-1 Buydown?
A 2-1 buydown temporarily reduces the payment a buyer makes during the first two years of the mortgage.
For example, let’s say a buyer obtains a 30-year fixed mortgage with a 6.5% note rate.
With a 2-1 buydown:
Year 1: Payments are calculated using a rate 2 percentage points lower — 4.5%
Year 2: Payments are calculated using a rate 1 percentage point lower — 5.5%
Year 3 and beyond: Payments are based on the full 6.5% note rate
One important distinction: the actual note rate isn’t changing every year.
In this example, the mortgage has a 6.5% note rate from the beginning. Funds contributed toward the temporary buydown are placed into an account and used to subsidize part of the buyer’s monthly payment during the first two years.
What Could That Look Like on an $800,000 Loan?
Here’s a simplified example using an $800,000, 30-year fixed-rate mortgage with a 6.5% note rate:
| Period | Payment Rate | Approx. Monthly Principal & Interest |
|---|---|---|
| Year 1 | 4.5% | $4,053 |
| Year 2 | 5.5% | $4,542 |
| Year 3+ | 6.5% | $5,057 |
During the first year, that’s approximately $1,004 less per month compared with the payment at the full note rate.
During the second year, the difference is approximately $515 per month.
In this simplified example, funding those payment differences for the first two years would require approximately $18,200.
These figures are for illustration only and don’t include property taxes, homeowners insurance, HOA dues, mortgage insurance, or other housing expenses. Actual rates, payments, buydown costs, and eligibility should be determined by the buyer’s lender.
Who Pays for a 2-1 Buydown?
Depending on the loan program and transaction, a temporary buydown may be funded by an eligible third party, such as a seller or builder.
This is where the strategy can become interesting in a real estate negotiation.
Suppose a buyer likes a property but is concerned about the monthly payment. Instead of negotiating solely over the purchase price, the buyer and seller could potentially negotiate an allowable seller credit that helps fund a temporary buydown.
The seller gets another tool for negotiating the transaction, while the buyer gets some payment relief during the first two years.
Why Would a Buyer Consider a 2-1 Buydown?
The obvious advantage is a lower initial monthly payment.
The first couple of years after buying a home can come with plenty of additional expenses—moving, furniture, improvements, repairs, and simply adjusting to a new housing payment.
A temporary buydown can provide some breathing room during that period.
However, buyers need to look beyond the first-year payment.
The important question isn’t:
“Can I afford the payment in Year 1?”
It’s:
“Am I comfortable with the full payment once the temporary buydown ends?”
Under Fannie Mae’s temporary buydown guidelines, for example, qualifying is generally based on the full note rate, rather than the temporarily reduced payment.
Why Would a Seller Offer a 2-1 Buydown?
This is where I think the strategy becomes especially useful for sellers.
Imagine receiving an offer where the buyer asks you to reduce your price by $20,000.
Before automatically agreeing to the price reduction, there may be another conversation worth having.
Could some of that negotiating power instead be used toward an allowable seller credit that helps reduce the buyer’s payments during the first two years?
Depending on the buyer’s financing and circumstances, that could have a much more noticeable short-term impact on their monthly housing expense than simply reducing the purchase price.
That doesn’t mean a 2-1 buydown is always better than a price reduction.
It simply gives buyers and sellers another negotiating tool.
Price Reduction vs. 2-1 Buydown
These two strategies accomplish different things.
A price reduction permanently lowers the purchase price and may reduce the buyer’s loan amount and monthly payment.
A 2-1 buydown doesn’t necessarily reduce the purchase price. Instead, it uses funds upfront to temporarily subsidize the buyer’s mortgage payments.
Which strategy makes more sense depends on factors such as:
- Purchase price
- Loan amount
- Interest rate
- Down payment
- Available seller credits
- Loan program
- Appraisal
- Buyer’s long-term plans
- Seller’s desired net proceeds
This is why it’s helpful for the buyer’s lender and real estate agent to run the numbers before deciding how to structure an offer.
What Happens After Two Years?
This is probably the most important part for buyers to understand.
A 2-1 buydown is temporary.
Once the buydown period ends, the buyer is responsible for making the full payment associated with the mortgage’s note rate.
Some buyers may hope that mortgage rates decline enough to refinance before then. That could happen, but it shouldn’t be assumed.
Future interest rates aren’t guaranteed, and refinancing generally involves qualification requirements and costs.
A buyer should therefore be comfortable with the original loan terms even if refinancing never becomes attractive or available.
Are There Restrictions?
Yes.
Temporary buydowns must comply with the requirements of the buyer’s specific loan program and lender.
For example, Fannie Mae permits temporary interest-rate buydowns on certain fixed-rate mortgages secured by principal residences and second homes, but not investment properties under its temporary-bydown guidelines.
There are also rules surrounding interested-party contributions and how much a seller or other party can contribute toward a buyer’s financing and closing costs.
That’s why the lender should be involved before structuring the offer around a 2-1 buydown.
Is a 2-1 Buydown Worth Considering?
For the right transaction, absolutely worth exploring.
For buyers, it can provide temporary relief from the full mortgage payment during the first two years.
For sellers, it can provide another negotiating option when a buyer is concerned about affordability—potentially allowing the parties to structure a deal without relying exclusively on a price reduction.
But it isn’t a one-size-fits-all solution.
The best approach is to compare the actual numbers.
What happens if we reduce the price?
What happens if we negotiate a seller credit?
What would a 2-1 buydown cost?
What would the buyer’s payment look like in Years 1, 2 and 3?
Once you put those options side by side, it’s much easier for both parties to make an informed decision.
Buying or Selling a Home in Orange County?
If you’re considering buying or selling a home in Huntington Beach or elsewhere in Orange County, strategies like a temporary mortgage buydown are worth understanding—especially when mortgage rates are affecting affordability.
For sellers, we can look beyond simply lowering the asking price and evaluate different ways to make your property and the terms of the sale attractive to buyers.
For buyers, we can work with your lender to understand how different purchase prices, credits, and financing strategies could affect your monthly payment.
Thinking about buying or selling? Reach out and let’s look at the numbers and determine which options make sense for your situation.
This article is for general educational purposes only and is not mortgage, financial, tax, or legal advice. Mortgage programs, rates, eligibility requirements, seller-contribution limits, and buydown terms can change. Buyers should consult a qualified mortgage professional regarding their specific financing options.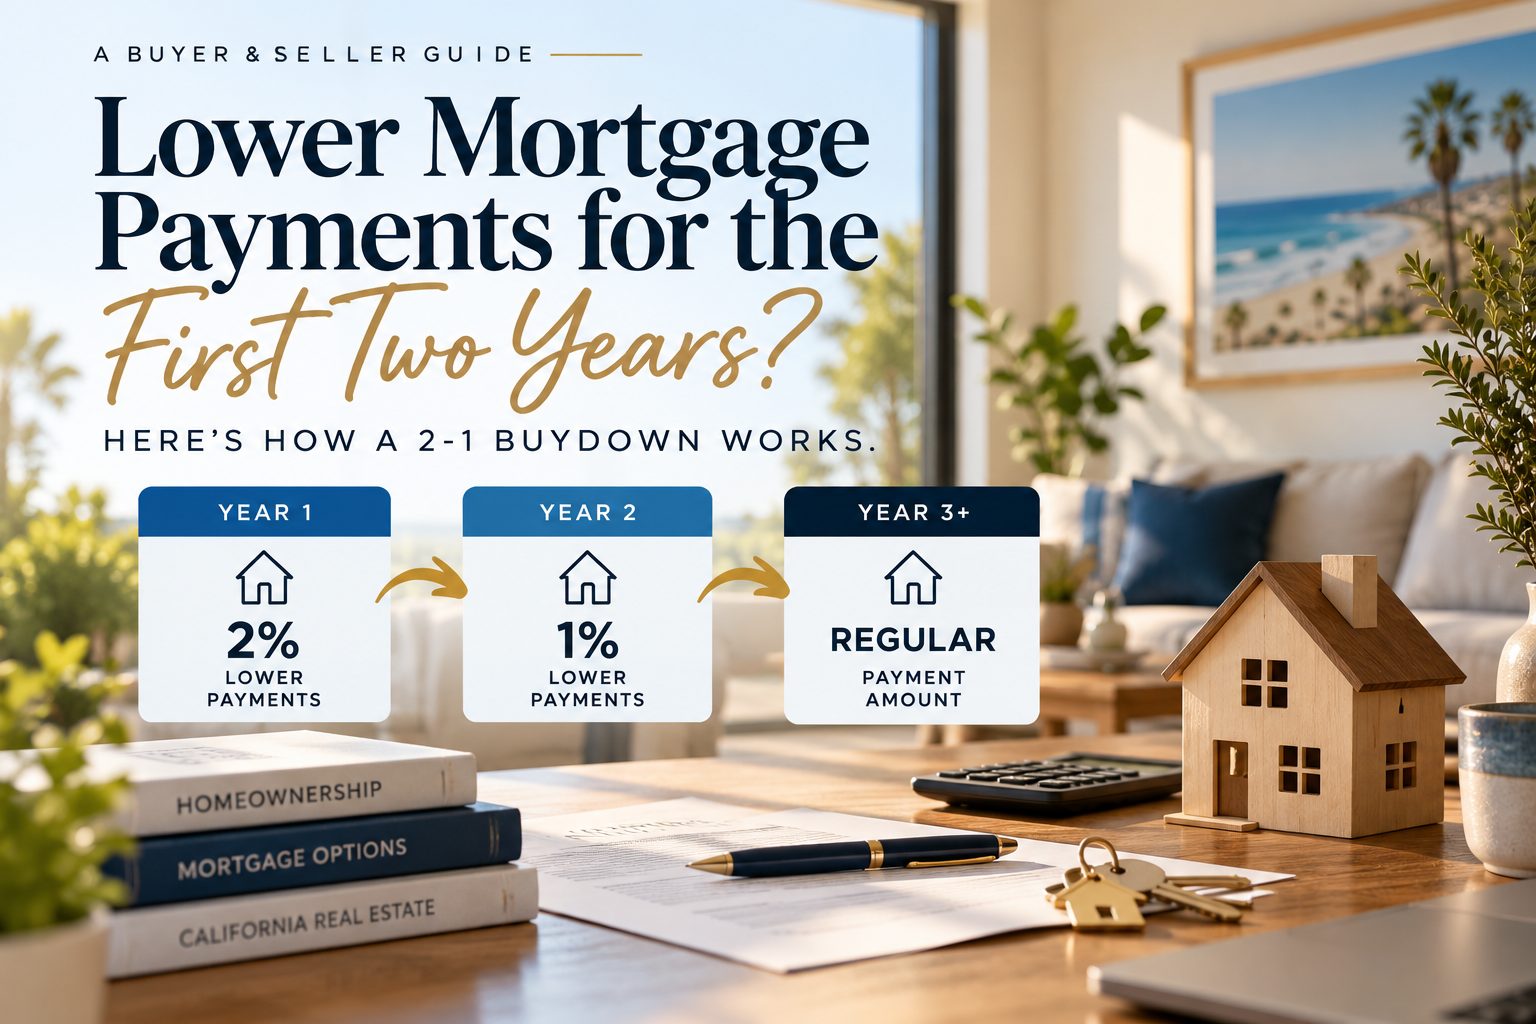
Selling Your California Home? Here Are the Costs to Expect
If you’re thinking about selling your home, you probably have two numbers on your mind: What is my home worth, and how much money will I actually walk away with?
Those numbers aren’t necessarily the same.
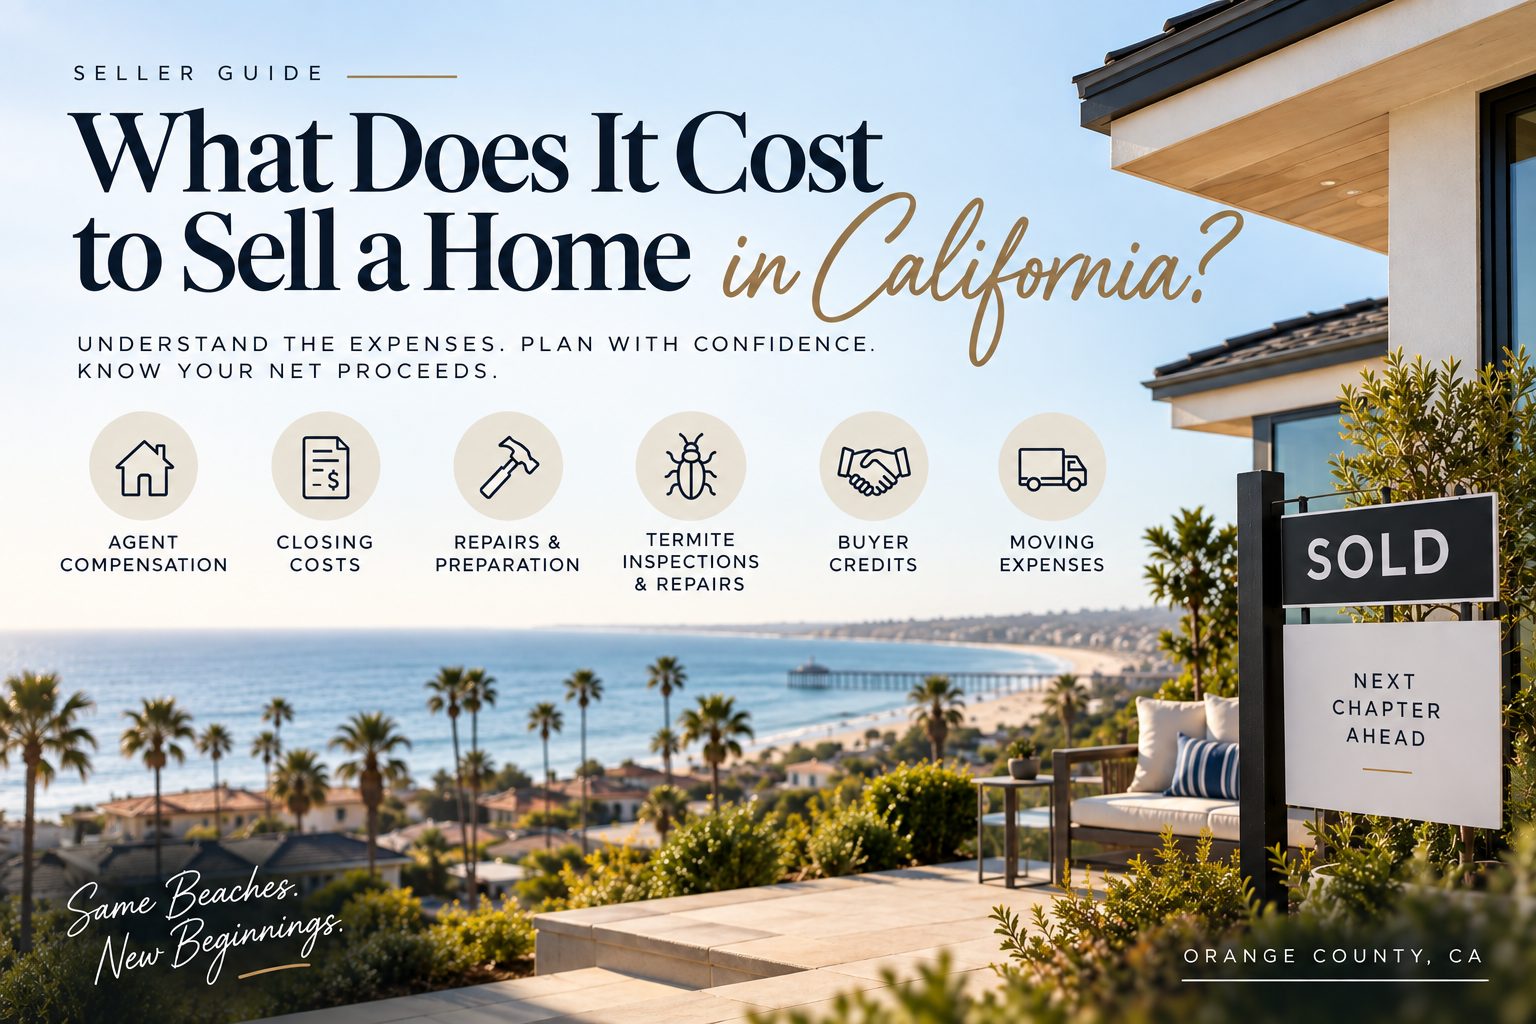
There are several expenses that can come with selling a home in California. Some are fairly predictable, while others depend on the condition of your property, the terms of the offer, and what you negotiate with the buyer.
Understanding these expenses before putting your home on the market can help you avoid surprises and make better decisions throughout the sale.
1. Real Estate Agent Compensation
Real estate agent compensation is negotiable and depends on the agreement between the seller and their agent, as well as any other compensation negotiated as part of the transaction.
When interviewing an agent, don’t just ask what they charge. Ask what services are included.
Depending on the agent and their marketing plan, those services may include professional photography, video, social media marketing, online advertising, open houses, MLS exposure, showing coordination, pricing strategy, offer analysis, negotiation, and transaction management.
The goal isn’t simply to get your home on the market. It’s to properly position the property, attract qualified buyers, negotiate favorable terms, and successfully get the transaction through closing.
2. Escrow, Title and Other Closing Costs
Sellers can also have various expenses associated with transferring ownership of the property.
Depending on the transaction and local customs, these may include escrow fees, title-related expenses, transfer taxes, HOA-related fees, document fees, and prorated property taxes or assessments.
The exact amount will vary from one sale to another.
That’s why I prefer preparing an estimated seller net sheet before listing. Instead of guessing based on a percentage, we can look at the anticipated sale price and estimated expenses to give you a much clearer picture of your potential proceeds.
3. Preparing Your Home for the Market
This is one area where sellers often have quite a bit of control.
You may decide to spend money on things like:
- Interior or exterior paint
- Professional cleaning
- Landscaping
- Carpet or flooring
- Handyman repairs
- Window cleaning
- Decluttering and storage
- Staging
- Pre-listing inspections
The key is determining which improvements are worth doing and which aren’t.
You don’t necessarily need to remodel your kitchen or bathrooms before selling. Sometimes relatively inexpensive improvements—fresh paint, landscaping, cleaning, and decluttering—can make a significant difference in how buyers perceive the home.
Before spending thousands of dollars on renovations, it’s a good idea to talk with your real estate agent about what buyers are looking for in your particular neighborhood and price range.
4. Termite Inspection and Repairs
Here in California, termites and other wood-destroying organisms are something homeowners frequently encounter.
Depending on the property, a termite inspection may identify items such as drywood termites, subterranean termites, fungus, dry rot, or other wood damage.
The cost can vary significantly. A property might require relatively minor repairs or treatment, while another could require more extensive work.
It’s also important to understand that termite inspections and repairs aren’t automatically handled the same way in every transaction. Whether an inspection is performed, who pays for repairs, and which items are completed can depend on the contract and negotiations between the buyer and seller.
For some sellers, addressing termite issues before listing can help eliminate uncertainty. For others, it may make more sense to address them during negotiations.
5. Buyer-Requested Repairs and Credits
After accepting an offer, the buyer will typically conduct their inspections and due diligence according to the terms of the purchase agreement.
Depending on what they discover, the buyer may request that certain items be repaired or ask for a credit instead.
For example, an inspection might identify an aging water heater, plumbing issue, roof concern, electrical item, or other deferred maintenance.
That doesn’t automatically mean the seller has to agree to every request. Repairs and credits can become part of the negotiation between buyer and seller.
This is also why the highest-priced offer isn’t necessarily always the offer that produces the best financial outcome. Price, contingencies, credits, repairs, financing, and other terms can all affect your final proceeds.
6. Moving and Other Expenses
Don’t forget about the costs associated with actually moving out of the property.
Depending on your situation, you might need movers, packing supplies, temporary storage, junk removal, or even temporary housing.
Individually, these expenses may not seem significant compared with the value of the home, but they’re still worth including when planning your move.
The Number Sellers Should Really Pay Attention To
When I meet with homeowners, I don’t think the conversation should stop at:
“How much can we sell my house for?”
There’s another question that’s just as important:
“How much will I actually walk away with?”
That’s where an estimated seller net sheet becomes valuable.
We can start with an anticipated sales price and estimate the expenses associated with the transaction, along with any mortgage or other liens that need to be paid off.
Estimated Sales Price
– Selling Expenses
– Mortgage & Other Payoffs
= Estimated Net Proceeds
That gives you a much more useful number when you’re deciding whether to sell and planning what comes next.
Thinking About Selling Your Orange County Home?
If you’re considering selling a home in Huntington Beach or elsewhere in Orange County, I recommend looking at the numbers before putting the property on the market.
We can discuss your home’s estimated value, what—if anything—you should repair or improve before listing, your marketing and pricing strategy, and your estimated net proceeds.
That way, you’re not going into the sale wondering what everything is going to cost.
You’ll have a plan.
Thinking about selling? Contact me and I’d be happy to prepare a complimentary home value analysis and estimated seller net sheet so you can see what your numbers may look like before making a decision.
This article is for general informational purposes. Costs, contractual obligations, taxes, and transaction terms vary. Sellers should consult the appropriate real estate, tax, legal, or other professionals regarding their specific situation.