Facebook
 X
 Pinterest
 Copy Link
With mortgage rates playing such a big role in affordability, buyers and sellers are looking for creative ways to put a deal together without necessarily relying on a large price reduction.
One option you may hear about is a 2-1 temporary mortgage rate buydown.
A 2-1 buydown can lower a buyer’s mortgage payment during the first two years of homeownership. And in some transactions, a seller may be able to provide a credit that helps fund it.
So, how does it work—and when might it make sense?
What Is a 2-1 Buydown?
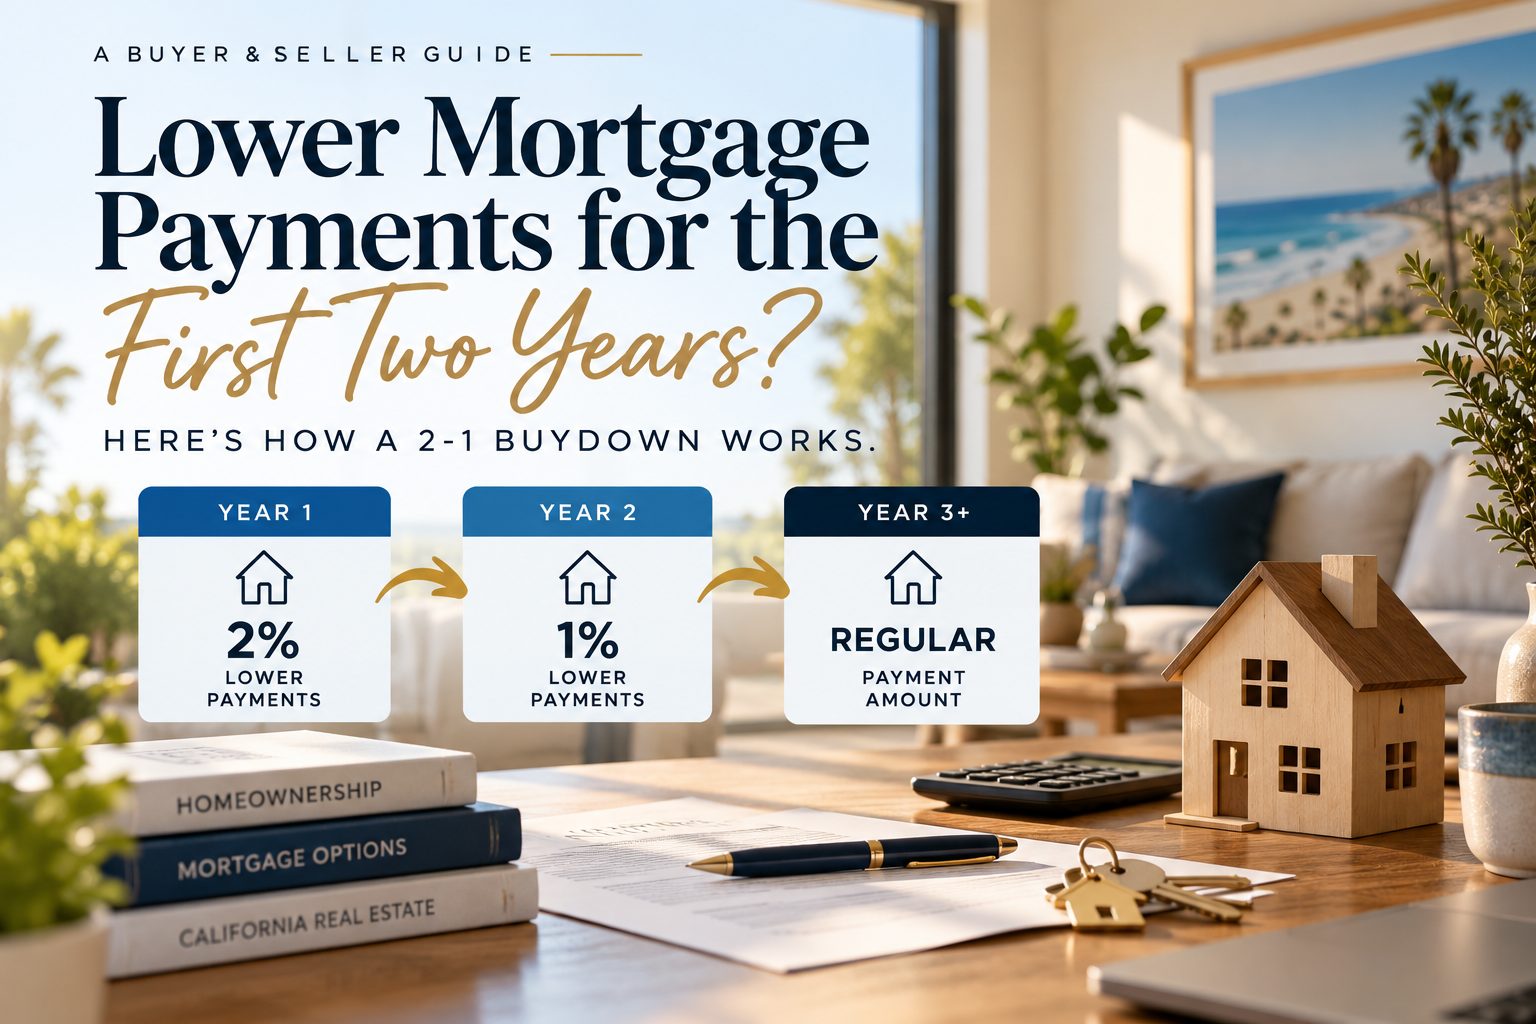
A 2-1 buydown temporarily reduces the payment a buyer makes during the first two years of the mortgage.
For example, let’s say a buyer obtains a 30-year fixed mortgage with a 6.5% note rate.
With a 2-1 buydown:
Year 1: Payments are calculated using a rate 2 percentage points lower — 4.5%
Year 2: Payments are calculated using a rate 1 percentage point lower — 5.5%
Year 3 and beyond: Payments are based on the full 6.5% note rate
One important distinction: the actual note rate isn’t changing every year.
In this example, the mortgage has a 6.5% note rate from the beginning. Funds contributed toward the temporary buydown are placed into an account and used to subsidize part of the buyer’s monthly payment during the first two years.
What Could That Look Like on an $800,000 Loan?
Here’s a simplified example using an $800,000, 30-year fixed-rate mortgage with a 6.5% note rate:
| Period | Payment Rate | Approx. Monthly Principal & Interest |
|---|---|---|
| Year 1 | 4.5% | $4,053 |
| Year 2 | 5.5% | $4,542 |
| Year 3+ | 6.5% | $5,057 |
During the first year, that’s approximately $1,004 less per month compared with the payment at the full note rate.
During the second year, the difference is approximately $515 per month.
In this simplified example, funding those payment differences for the first two years would require approximately $18,200.
These figures are for illustration only and don’t include property taxes, homeowners insurance, HOA dues, mortgage insurance, or other housing expenses. Actual rates, payments, buydown costs, and eligibility should be determined by the buyer’s lender.
Who Pays for a 2-1 Buydown?
Depending on the loan program and transaction, a temporary buydown may be funded by an eligible third party, such as a seller or builder.
This is where the strategy can become interesting in a real estate negotiation.
Suppose a buyer likes a property but is concerned about the monthly payment. Instead of negotiating solely over the purchase price, the buyer and seller could potentially negotiate an allowable seller credit that helps fund a temporary buydown.
The seller gets another tool for negotiating the transaction, while the buyer gets some payment relief during the first two years.
Why Would a Buyer Consider a 2-1 Buydown?
The obvious advantage is a lower initial monthly payment.
The first couple of years after buying a home can come with plenty of additional expenses—moving, furniture, improvements, repairs, and simply adjusting to a new housing payment.
A temporary buydown can provide some breathing room during that period.
However, buyers need to look beyond the first-year payment.
The important question isn’t:
“Can I afford the payment in Year 1?”
It’s:
“Am I comfortable with the full payment once the temporary buydown ends?”
Under Fannie Mae’s temporary buydown guidelines, for example, qualifying is generally based on the full note rate, rather than the temporarily reduced payment.
Why Would a Seller Offer a 2-1 Buydown?
This is where I think the strategy becomes especially useful for sellers.
Imagine receiving an offer where the buyer asks you to reduce your price by $20,000.
Before automatically agreeing to the price reduction, there may be another conversation worth having.
Could some of that negotiating power instead be used toward an allowable seller credit that helps reduce the buyer’s payments during the first two years?
Depending on the buyer’s financing and circumstances, that could have a much more noticeable short-term impact on their monthly housing expense than simply reducing the purchase price.
That doesn’t mean a 2-1 buydown is always better than a price reduction.
It simply gives buyers and sellers another negotiating tool.
Price Reduction vs. 2-1 Buydown
These two strategies accomplish different things.
A price reduction permanently lowers the purchase price and may reduce the buyer’s loan amount and monthly payment.
A 2-1 buydown doesn’t necessarily reduce the purchase price. Instead, it uses funds upfront to temporarily subsidize the buyer’s mortgage payments.
Which strategy makes more sense depends on factors such as:
- Purchase price
- Loan amount
- Interest rate
- Down payment
- Available seller credits
- Loan program
- Appraisal
- Buyer’s long-term plans
- Seller’s desired net proceeds
This is why it’s helpful for the buyer’s lender and real estate agent to run the numbers before deciding how to structure an offer.
What Happens After Two Years?
This is probably the most important part for buyers to understand.
A 2-1 buydown is temporary.
Once the buydown period ends, the buyer is responsible for making the full payment associated with the mortgage’s note rate.
Some buyers may hope that mortgage rates decline enough to refinance before then. That could happen, but it shouldn’t be assumed.
Future interest rates aren’t guaranteed, and refinancing generally involves qualification requirements and costs.
A buyer should therefore be comfortable with the original loan terms even if refinancing never becomes attractive or available.
Are There Restrictions?
Yes.
Temporary buydowns must comply with the requirements of the buyer’s specific loan program and lender.
For example, Fannie Mae permits temporary interest-rate buydowns on certain fixed-rate mortgages secured by principal residences and second homes, but not investment properties under its temporary-bydown guidelines.
There are also rules surrounding interested-party contributions and how much a seller or other party can contribute toward a buyer’s financing and closing costs.
That’s why the lender should be involved before structuring the offer around a 2-1 buydown.
Is a 2-1 Buydown Worth Considering?
For the right transaction, absolutely worth exploring.
For buyers, it can provide temporary relief from the full mortgage payment during the first two years.
For sellers, it can provide another negotiating option when a buyer is concerned about affordability—potentially allowing the parties to structure a deal without relying exclusively on a price reduction.
But it isn’t a one-size-fits-all solution.
The best approach is to compare the actual numbers.
What happens if we reduce the price?
What happens if we negotiate a seller credit?
What would a 2-1 buydown cost?
What would the buyer’s payment look like in Years 1, 2 and 3?
Once you put those options side by side, it’s much easier for both parties to make an informed decision.
Buying or Selling a Home in Orange County?
If you’re considering buying or selling a home in Huntington Beach or elsewhere in Orange County, strategies like a temporary mortgage buydown are worth understanding—especially when mortgage rates are affecting affordability.
For sellers, we can look beyond simply lowering the asking price and evaluate different ways to make your property and the terms of the sale attractive to buyers.
For buyers, we can work with your lender to understand how different purchase prices, credits, and financing strategies could affect your monthly payment.
Thinking about buying or selling? Reach out and let’s look at the numbers and determine which options make sense for your situation.
This article is for general educational purposes only and is not mortgage, financial, tax, or legal advice. Mortgage programs, rates, eligibility requirements, seller-contribution limits, and buydown terms can change. Buyers should consult a qualified mortgage professional regarding their specific financing options.